The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Insurance brokers, agents and direct insurers can all help Australians arrange cover, but they do not play the same role. Understanding who they act for, how they are paid and what options they can access can help consumers and small business owners choose the right path for their insurance needs.
Why the difference matters
When you are comparing insurance, the person or organisation you deal with can affect the range of options you see, the type of guidance you receive and who assists you if you need to make a claim. An insurance broker, an insurance agent and a direct insurer may all discuss policies, premiums and cover, but they sit in different parts of the insurance market.
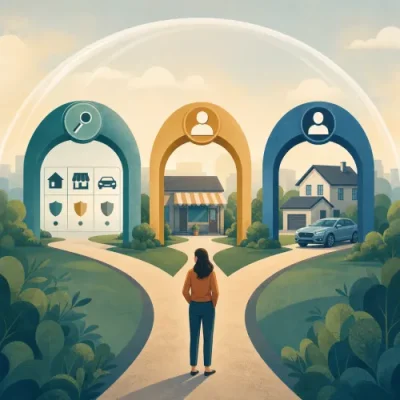
The short version is this: an insurance broker generally helps a client consider cover from more than one insurer or insurance market, while an agent usually represents an insurer or another insurance provider. Buying directly means you deal with the insurer or its direct sales channel yourself. Each path can be appropriate in different circumstances, depending on the complexity of your risks, the type of cover you need, your budget and how much support you want.
This article provides general educational information for Australian consumers and small business owners. It does not take into account your personal objectives, financial situation or needs, and insurance availability, pricing and terms depend on provider criteria and your individual circumstances.
What is an insurance broker?
An insurance broker is an intermediary who helps clients identify insurance needs, compare available cover and arrange policies. In Australia, brokers commonly assist with business insurance, professional indemnity, public liability, commercial property, home and contents, motor, farm, strata and other forms of general insurance. Some brokers may also specialise in particular industries or policy types.
A broker's role can include:
- asking questions about your assets, activities, liabilities and risk exposures;
- explaining what different types of insurance are designed to cover;
- seeking quotes or policy options from insurers or underwriting agencies they can access;
- helping you compare premiums, excesses, exclusions, limits and policy conditions;
- arranging cover once you choose an option;
- helping with renewals, policy changes and sometimes claims support.
Brokers do not have access to every insurer or every product in the Australian market. Their recommendations are usually limited to the insurers, underwriting agencies and markets they can deal with. That is why it is useful to ask a broker which insurers they commonly approach, whether they use a panel of insurers and whether any relevant products are outside their usual market access.
If you are looking for broker assistance, you can start by exploring the Insurance Finder Australia homepage or browsing the site's broker listings to understand how broker information may be presented.
What is an insurance agent?
An insurance agent usually acts for an insurer, underwriting agency or another insurance provider rather than acting as a broad market representative for the customer. The agent may sell, administer or service insurance products on behalf of the provider that has appointed them.
For example, an agent may be authorised to arrange policies for one insurer or for a particular insurance brand. They may understand that provider's products in detail, but they may not be able to compare your options across a wide range of competing insurers.
The term "agent" is sometimes used loosely in everyday conversation, so it is worth asking exactly who the person represents. A useful question is: Are you acting on behalf of me, the insurer, or another licensee? The answer can help you understand the scope of their service and whether their product range is broad or limited.
What is a direct insurer?
A direct insurer sells policies directly to customers, usually through its own website, call centre, branch network or digital quote process. When you buy direct, you are dealing with the insurer or its representatives without using an independent broker to search the market for you.
Buying direct may suit people who already understand the cover they want, have relatively straightforward needs and are comfortable reading the Product Disclosure Statement, exclusions, limits and conditions themselves. It can also be convenient when you want to deal with a single insurer from quote through to renewal.
The limitation is that a direct insurer generally offers its own products. It may explain differences within its own product suite, but it is not usually comparing your needs against a broad range of competing insurers. If your situation is complex, unusual or business-related, you may need to do more work yourself to understand whether a direct policy fits your risks.
Insurance broker vs agent vs direct insurer in Australia
The main difference is who they usually represent and how wide their product access may be. The table below summarises the practical differences.
| Channel |
Who they usually act for |
Typical product access |
Potential advantages |
Potential limitations |
| Insurance broker |
The client, although you should confirm the arrangement and any conflicts |
Multiple insurers, underwriting agencies or specialist markets, depending on the broker |
Can help assess needs, compare options, explain policy terms and support renewals or claims |
May charge fees, receive commissions or both; does not access every product in the market |
| Insurance agent |
An insurer, underwriting agency or provider that appoints them |
Usually limited to the provider or product range they are authorised to offer |
May have detailed knowledge of that provider's products and processes |
May not compare your needs across a broad market |
| Direct insurer |
The insurer selling its own products |
The insurer's own policies and options |
Can be convenient for straightforward cover and direct policy management |
You usually need to compare alternatives, exclusions and suitability yourself |
| Comparison or referral service |
Varies by business model |
Usually a selected panel, not the whole market |
Can help you see some options quickly |
May not provide personal advice or may only compare limited features, so check the service scope |
Where authorised representatives fit in
In Australian financial services, you may also come across the term authorised representative. This is not the same thing as being a broker or an agent. An authorised representative is a person or business authorised by an Australian financial services licensee to provide specified financial services under that licence.
An authorised representative could work within a broking business, for an underwriting agency, for an insurer-related business or for another licensed financial services organisation. The label tells you that they are authorised under a licence arrangement, but it does not automatically tell you whose interests they represent in a commercial sense or how broad their product access is.
When dealing with any insurance professional, you can ask:
- What Australian financial services licence or authorised representative arrangement applies?
- What types of insurance are you authorised to discuss or arrange?
- Do you act for me, for an insurer, or for another provider?
- How are you paid for arranging or servicing the policy?
- Which insurers or markets do you use, and are any relevant insurers excluded?
How brokers, agents and direct insurers are paid
Payment arrangements vary, and they can influence how you compare options. Insurance brokers may receive commission from insurers, charge a broker fee to the client, charge service fees, or use a combination of these. Agents are often paid by the insurer or provider they represent. Direct insurers price and sell their own products, so distribution costs are built into their business model in different ways.
Before you agree to proceed, ask for a clear explanation of fees, commissions and any other charges. You can also ask what happens if you cancel, change your policy mid-term or renew through the same channel. For retail clients, important information may be provided in documents such as a Financial Services Guide, quote documents and the relevant Product Disclosure Statement.
It is also worth understanding the word independent. In Australia, "independent" has a specific regulatory meaning in financial services. A broker may compare multiple insurers and still not describe themselves as independent if they receive commissions or have other arrangements that prevent them from using that term. Rather than relying on the label, ask how the broker is paid and what products they can consider.
What each channel may help with
When a broker may be useful
A broker may be worth considering when your insurance needs are complex, specialised or difficult to compare. This often applies to small businesses, contractors, professionals, landlords, farms, strata properties, high-value assets or situations where exclusions and policy wording matter as much as the premium.
For example, a small business owner may need to consider public liability, property, business interruption, cyber cover and professional indemnity. A broker can help explain how these policies differ, where gaps may arise and how insurers may view the business's activities. The final availability and terms of cover still depend on insurer criteria and underwriting decisions.
If your focus is business cover, the guide on how to choose the right insurance broker for your business explains additional questions to ask when comparing broker services, industry experience and communication style.
When an agent may be suitable
An agent may be suitable if you want a specific provider's product and you need help understanding that provider's application process, policy options or service procedures. Agents can be useful where the product range is narrow and you already know the insurer or brand you prefer.
The key is to recognise that an agent's role is usually tied to the provider they represent. If you want broader market comparison, you may need to speak with a broker or compare other insurers yourself.
When buying direct may be suitable
Buying direct may work for people who have simple insurance needs, are comfortable comparing policy documents and are confident they understand what is included and excluded. Many Australians buy direct for common personal insurance products such as car, home or contents insurance.
However, direct does not automatically mean cheaper, simpler or more suitable. Premiums, excesses and cover depend on the insurer's underwriting, your circumstances and the policy terms. A lower premium may come with higher excesses, narrower cover or exclusions that matter to you, so comparing only on price can be risky.
How to compare your options in practice
Whether you use a broker, an agent or a direct insurer, the same core questions can help you make a more informed decision:
- What risks am I trying to cover? List the assets, liabilities, income streams or business activities you want to protect.
- What is included and excluded? Read the policy wording carefully, including exclusions, limits, sub-limits, waiting periods and conditions.
- What excess applies? A higher excess may reduce premiums in some cases, but it also affects what you pay if you claim.
- How is the quote calculated? Premiums can depend on location, claims history, occupation, business activities, property details, sums insured and other underwriting factors.
- Who will help if I need to claim? Ask whether the broker, agent or insurer will assist with claims and what that support includes.
- How are conflicts managed? Ask about commissions, referral payments, ownership links and preferred insurer arrangements.
- What happens at renewal? Check whether your cover will be reviewed, automatically renewed or requoted.
It can also help to separate three decisions: the type of insurance you need, the amount or limit of cover you choose and the channel you use to arrange it. A broker can assist with those questions, but you still need to review the information provided and decide whether to proceed.
Common misunderstandings
"A broker always compares every insurer"
Brokers can often access multiple insurers or specialist markets, but no broker compares every possible policy in Australia. Their market access depends on their licence arrangements, insurer relationships, expertise and the type of cover being arranged. Ask which insurers were approached and why particular options were recommended.
"Direct insurance is always cheaper"
There is no reliable rule that direct insurance is always cheaper or more expensive than cover arranged through a broker. Premiums depend on underwriting criteria, policy features, distribution model, commissions, fees, excesses and your individual circumstances. Compare the total cost and the cover provided, not just the headline premium.
"Agents and brokers do the same thing"
Agents and brokers may both discuss insurance, but their roles can differ significantly. An agent is commonly connected to a specific insurer or provider, while a broker usually helps the client consider options from more than one market. Always confirm the relationship before relying on the service.
"Authorised representative means independent adviser"
Being an authorised representative means the person or business is authorised under an Australian financial services licence arrangement. It does not, by itself, mean they are independent or that they compare a broad range of insurers. Ask who the licensee is, what products they can arrange and how they are paid.
Which path should you choose?
There is no single right channel for every person or business. A broker may be useful if you want help assessing risks, comparing policy wording and dealing with more complex insurance needs. An agent may be appropriate if you are interested in a specific provider's product and want help with that product. A direct insurer may suit you if your needs are straightforward and you are comfortable doing your own comparison and document review.
Before deciding, consider how much advice or assistance you need, how complex your risks are, whether you want access to multiple insurers and how confident you are reading policy documents. Insurance is not only about finding a premium you can afford; it is also about understanding what the policy is designed to do, what it does not cover and how it may respond if something goes wrong.
If you decide that broker assistance may be useful, compare brokers as carefully as you compare insurance policies. Look at their licensing arrangements, experience, product access, fee disclosure, claims support and communication style. The right fit depends on your needs, the type of cover and the broker's services and expertise.
Published: Thursday, 25th Dec 2025
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.